THE VOICE FOR IOWA'S FUEL and Convenience store INDUSTRY


Fueling Iowa's Economy • Serving Iowa's Communities • Advocating for fuel and convenience retail

ADVOCACY

A strong voice for Iowa’s fuel and convenience store industry. We represent your interests at the State Capitol & in Washington D.C through EMA on the issues that impact your business.


BUSINESS SOLUTIONS

Programs built to save you money, reduce risk and make doing business easier. Explore FUELIowa solutions for insurance, benefits, safety & compliance, renewable fuels and more.

MARKETPLACE


Find trusted products, services and industry partners for your business. Connect with suppliers and solution providers that understand Iowa’s fuel and convenience store industry.


MEMBERSHIP


Put FUELIowa to work for your business. Join Iowa’s fuel and convenience store community for advocacy, business solutions, industry information, events and valuable connections.


Join Us. Stronger Together.

Put FUELIowa to Work for Your Business.
Diamond Partners

RINAlliance

Emerald Partners


Platinum Partners

Reynolds logo with the tagline “A BETTER TOMORROW”
Altria
Gallagher
Logo for Unified Contracting Services, Inc. with website petroleumcontractor.com

Gold Partners

Chevron and Renewable Energy Group logos
Health Alliance Benefit Plan
Sinclair
Otter Creek Country Store
Chevron and Renewable Energy Group logos
Health Alliance Benefit Plan

Latest from FUELIowa

By Sarah Bowman • October 26, 2026
EMA Regulatory Alert
By John Maynes • October 20, 2026
On Thursday, October 15, 2026, the Iowa Department of Revenue (IDR) issued further guidance following the proclamation issued by Governor Kim Reynolds on October 5, 2026, and expanded on October 6, 2026. The IDR guidance can be viewed here. The guidance issued by IDR makes clear that dyed diesel fuel gallons used for an on-road purpose during the term of Governor Reynolds proclamation will be subject to repayment of the 6 percent sales tax after the proclamation expires on February 4, 2027 . As the proclamation relates to sales tax, end-users should treat relief granted under the proclamation as a deferment of payment in lieu of an outright exemption. Regarding state motor fuel excise tax ($32.5 cpg), IDR does not anticipate recouping the state excise tax that would otherwise be due for on-road use of dyed diesel fuel after the proclamation expires. FUELIowa members should encourage customers to exercise caution around the use of dyed diesel fuel for an on-road purpose following the guidance issued by IDR. All dyed diesel fuel transfers between FUELIowa members and end-use customers should be documented with an Iowa Sales Tax Exemption Certificate signed by your end-use customer. A sales tax exemption certificate can be found here. By using this approach, FUELIowa members are not placed in a position of having to decipher between dyed diesel fuel gallons consumed by an end-user between on-road use and off-road use and the end-user is responsible for documenting and remitting the state sales tax owed after February 4, 2027.
By Sarah Bowman • October 15, 2026
Thursday, October 15, 2026 – The IRS announced Wednesday evening that it will not impose federal penalties when dyed diesel fuel is sold for highway use or used in diesel-powered vehicles on public highways nationwide. The announcement implements President Trump’s October 5, 2026, Executive Order 14435, “Emergency Tax Relief on Diesel Fuel.” The IRS announcement states that its penalty relief is retroactive to October 1, 2026, and remains in effect through December 31, 2026. The October 1 date comes from the IRS announcement; the Executive Order itself specifies an October 5 start date. Forthcoming payment-deferral guidance under Internal Revenue Code § 7508A may track the Executive Order’s October 5 date, in which case, fuel sold between October 1 and 4 would be free of penalties but would not eligible for any payment deferral. Penalties, Inspections and Recordkeeping Ordinarily, dyed diesel fuel is exempt from federal excise tax because it is intended for exempt uses, such as farming and in off-highway machinery. Federal law generally imposes tax when dyed diesel is sold for highway use or used in a diesel-powered on-highway vehicle. The retailer that sells dyed diesel for highway use is generally liable for the tax; where the fuel is not purchased at retail, such as fuel drawn from a farm storage tank, the vehicle operator is liable. During the relief period, the IRS states that it will not impose penalties related to the federal excise tax on dyed diesel fuel sold for highway use or used in highway vehicles. This includes penalties for failure to make required semimonthly tax deposits and failure to maintain adequate records. The Service also announced that it will suspend its ordinary collection and enforcement procedures during the relief period, that IRS Fuel Compliance Officers will be reassigned to other responsibilities, and that no federal inspections of on-road dyed-fuel use will occur. Sellers and distributors are not required to investigate or document the ultimate end use of dyed diesel fuel sold during this period. The announcement also states that taxpayers need not maintain records necessary to substantiate their eligibility for this relief. That statement concerns eligibility for this particular relief and should not be read as a general suspension of other business, tax, or recordkeeping obligations. The Tax Has Not Yet Been Waived The announcement does not eliminate the underlying federal excise tax liability. The IRS anticipates issuing additional guidance addressing postponement of payments under Internal Revenue Code § 7508A for taxes imposed under § 4041; that postponement is not yet in effect. No forgiveness has been granted. The IRS states only that it will explore avenues to eliminate the obligation to pay deferred amounts, and permanent forgiveness will likely require legislation. The announcement also does not address interest on any tax that remains due. Forthcoming guidance is expected to explain how the relief applies to Form 720, Quarterly Federal Excise Tax Return, and other relevant forms. The fourth-quarter Form 720 is due January 31, 2027. Until additional guidance is issued, marketers should not assume that the underlying federal diesel tax has been forgiven or that related payment and filing obligations have been eliminated. State Taxes and Enforcement The relief applies only to federal taxes and penalties. It does not prevent states from imposing their own taxes or penalties for highway use of dyed diesel fuel. Although many states have announced similar relief, state requirements vary. EMA members should consult the applicable state agencies regarding the availability and scope of state-level relief. EPA Requirements and the End of the Relief Period The IRS relief is not an EPA fuel waiver. Prior IRS dyed-fuel waivers were limited to fuel meeting the 15-ppm sulfur standard, and dyed product sold for highway use should continue to meet the ultra-low sulfur diesel (ULSD) standard. Texas is the exception. EPA's October 5, 2026, emergency waiver suspends the ULSD and Texas Low Emission Diesel (TxLED) requirements for eligible engines through October 24, 2026. Higher-sulfur product must be segregated and carry EPA's misfueling warning. Federal penalties resume January 1, 2027. Because red dye can remain in vehicle tanks and retail storage for weeks, marketers should plan the transition back to clear product. What Members Should Consider Keep records anyway. Although the IRS will not require records to substantiate eligibility for the relief, marketers should continue tracking gallons of dyed diesel sold to highway vehicles, by date and location. If the deferred tax ultimately comes due, those records will be the best defense against an IRS estimate of liability. Make a deliberate pricing decision. Retailers that do not collect the 24.4-cent federal tax at the pump now may find it difficult to recover from customers later. Identify who is liable. The announcement does not define “retail.” For cardlock sales, bulk deliveries into fleet tanks, and mobile fueling, it may be unclear whether the seller or the operator owes the tax. Review contracts. Branded supply agreements, fleet card product codes, and insurance policies may restrict or affect the sale of dyed product through highway dispensers. EMA will continue to monitor Treasury and IRS guidance, particularly regarding payment postponement, potential tax forgiveness, and the treatment of federal excise tax returns and deposits. Click here to read the IRS news release.

Regulatory Alert FMCSA Grants 90-Day Hours-of-Service Waiver for Gasoline and Diesel Hauls

September 17, 2026 by Energy Marketers of America

Thursday, September 17, 2026 – The Federal Motor Carrier Safety Administration has issued a 90-day hours-of-service waiver for motor carriers and drivers operating commercial motor vehicles in interstate commerce to transport gasoline and diesel fuel. The waiver took effect at 12:00 a.m. on September 16, 2026, and expires at 11:59 p.m. on December 16, 2026.

Reminder - E15 Access Mandate Safe Harbor Deadline

September 15, 2026

owa’s E15 mandate took effect January 1, 2026. Due to the scope of infrastructure work required, the Iowa Department of Agriculture and Land Stewardship (IDALS) established a safe harbor policy allowing retailers to extend their compliance deadline to September 30, 2026.


To qualify, retailers were required to provide evidence of an agreement with an Iowa-licensed installer for future E15 infrastructure work, such as an equipment purchase order, work order, installation agreement, contract, or invoice. A submitted, active application for an Iowa Renewable Fuels Infrastructure Program (RFIP) E15 cost-share grant also satisfied the requirement. All projects covered by safe harbor must be completed by September 30, 2026.


Safe harbor applies to an individual retail location and is separate from a Class I, Class II, or small retail facility waiver from Iowa’s E15 mandate.


FUELIowa members, including owners and licensed service professionals, experiencing challenges meeting the deadline should contact John Maynes to pursue a solution.

House Passes Common Cents Act

Iowa Vapor Products Directory to go Live on Thursday, October 15

October 13, 2026

By Sarah Bowman • October 26, 2026
EMA Regulatory Alert
By John Maynes • October 20, 2026
On Thursday, October 15, 2026, the Iowa Department of Revenue (IDR) issued further guidance following the proclamation issued by Governor Kim Reynolds on October 5, 2026, and expanded on October 6, 2026. The IDR guidance can be viewed here. The guidance issued by IDR makes clear that dyed diesel fuel gallons used for an on-road purpose during the term of Governor Reynolds proclamation will be subject to repayment of the 6 percent sales tax after the proclamation expires on February 4, 2027 . As the proclamation relates to sales tax, end-users should treat relief granted under the proclamation as a deferment of payment in lieu of an outright exemption. Regarding state motor fuel excise tax ($32.5 cpg), IDR does not anticipate recouping the state excise tax that would otherwise be due for on-road use of dyed diesel fuel after the proclamation expires. FUELIowa members should encourage customers to exercise caution around the use of dyed diesel fuel for an on-road purpose following the guidance issued by IDR. All dyed diesel fuel transfers between FUELIowa members and end-use customers should be documented with an Iowa Sales Tax Exemption Certificate signed by your end-use customer. A sales tax exemption certificate can be found here. By using this approach, FUELIowa members are not placed in a position of having to decipher between dyed diesel fuel gallons consumed by an end-user between on-road use and off-road use and the end-user is responsible for documenting and remitting the state sales tax owed after February 4, 2027.
By Sarah Bowman • October 15, 2026
Thursday, October 15, 2026 – The IRS announced Wednesday evening that it will not impose federal penalties when dyed diesel fuel is sold for highway use or used in diesel-powered vehicles on public highways nationwide. The announcement implements President Trump’s October 5, 2026, Executive Order 14435, “Emergency Tax Relief on Diesel Fuel.” The IRS announcement states that its penalty relief is retroactive to October 1, 2026, and remains in effect through December 31, 2026. The October 1 date comes from the IRS announcement; the Executive Order itself specifies an October 5 start date. Forthcoming payment-deferral guidance under Internal Revenue Code § 7508A may track the Executive Order’s October 5 date, in which case, fuel sold between October 1 and 4 would be free of penalties but would not eligible for any payment deferral. Penalties, Inspections and Recordkeeping Ordinarily, dyed diesel fuel is exempt from federal excise tax because it is intended for exempt uses, such as farming and in off-highway machinery. Federal law generally imposes tax when dyed diesel is sold for highway use or used in a diesel-powered on-highway vehicle. The retailer that sells dyed diesel for highway use is generally liable for the tax; where the fuel is not purchased at retail, such as fuel drawn from a farm storage tank, the vehicle operator is liable. During the relief period, the IRS states that it will not impose penalties related to the federal excise tax on dyed diesel fuel sold for highway use or used in highway vehicles. This includes penalties for failure to make required semimonthly tax deposits and failure to maintain adequate records. The Service also announced that it will suspend its ordinary collection and enforcement procedures during the relief period, that IRS Fuel Compliance Officers will be reassigned to other responsibilities, and that no federal inspections of on-road dyed-fuel use will occur. Sellers and distributors are not required to investigate or document the ultimate end use of dyed diesel fuel sold during this period. The announcement also states that taxpayers need not maintain records necessary to substantiate their eligibility for this relief. That statement concerns eligibility for this particular relief and should not be read as a general suspension of other business, tax, or recordkeeping obligations. The Tax Has Not Yet Been Waived The announcement does not eliminate the underlying federal excise tax liability. The IRS anticipates issuing additional guidance addressing postponement of payments under Internal Revenue Code § 7508A for taxes imposed under § 4041; that postponement is not yet in effect. No forgiveness has been granted. The IRS states only that it will explore avenues to eliminate the obligation to pay deferred amounts, and permanent forgiveness will likely require legislation. The announcement also does not address interest on any tax that remains due. Forthcoming guidance is expected to explain how the relief applies to Form 720, Quarterly Federal Excise Tax Return, and other relevant forms. The fourth-quarter Form 720 is due January 31, 2027. Until additional guidance is issued, marketers should not assume that the underlying federal diesel tax has been forgiven or that related payment and filing obligations have been eliminated. State Taxes and Enforcement The relief applies only to federal taxes and penalties. It does not prevent states from imposing their own taxes or penalties for highway use of dyed diesel fuel. Although many states have announced similar relief, state requirements vary. EMA members should consult the applicable state agencies regarding the availability and scope of state-level relief. EPA Requirements and the End of the Relief Period The IRS relief is not an EPA fuel waiver. Prior IRS dyed-fuel waivers were limited to fuel meeting the 15-ppm sulfur standard, and dyed product sold for highway use should continue to meet the ultra-low sulfur diesel (ULSD) standard. Texas is the exception. EPA's October 5, 2026, emergency waiver suspends the ULSD and Texas Low Emission Diesel (TxLED) requirements for eligible engines through October 24, 2026. Higher-sulfur product must be segregated and carry EPA's misfueling warning. Federal penalties resume January 1, 2027. Because red dye can remain in vehicle tanks and retail storage for weeks, marketers should plan the transition back to clear product. What Members Should Consider Keep records anyway. Although the IRS will not require records to substantiate eligibility for the relief, marketers should continue tracking gallons of dyed diesel sold to highway vehicles, by date and location. If the deferred tax ultimately comes due, those records will be the best defense against an IRS estimate of liability. Make a deliberate pricing decision. Retailers that do not collect the 24.4-cent federal tax at the pump now may find it difficult to recover from customers later. Identify who is liable. The announcement does not define “retail.” For cardlock sales, bulk deliveries into fleet tanks, and mobile fueling, it may be unclear whether the seller or the operator owes the tax. Review contracts. Branded supply agreements, fleet card product codes, and insurance policies may restrict or affect the sale of dyed product through highway dispensers. EMA will continue to monitor Treasury and IRS guidance, particularly regarding payment postponement, potential tax forgiveness, and the treatment of federal excise tax returns and deposits. Click here to read the IRS news release.

Upcoming Events

  —
December 2, 2026 Council Bluffs Regional Roundtable
1900 Madison Ave, Council Bluffs, IA 51503
  —
December 3, 2026 Carroll Regional Roundtable
Carrollton Inn, 1730 Hwy 71 North, Carroll, IA 51401
  —
December 9, 2026 Dubuque Regional Roundtable
Hotel Julien, 200 Main Street, Dubuque, IA 52001

FEATURED INDUSTRY PARTNER

FUELIowa has partnered with SAMSARA to bring their full range of fleet safety & management products & services to FUELIowa members at substantial discounts. Combining SAMSARA's Technology with FUELIowa's Safety Dividend Program is a powerful combination for our industry

About Us

Mission and Members

Formed in 1937, FUELIowa represents Iowa's fuel industry by advocating for innovative and quality fuel options, consumer and environmental protection and fairness in the marketplace.

Our members include fuel distributors, fuel cooperatives, convenience and grocery stores, refiners, biofuel producers and many other businesses that support these companies. They are invested in bringing the best gasoline, diesel, propane, ethanol, biodiesel and other liquid fuels to Iowans. 

View the Alternative Fuels Locator to find locations throughout the state of Iowa.


Beliefs and Values

FUELIowa believes a strong, accessible fuel distribution network is essential to Iowa’s rural and urban economies. We value fuel choice, fuel quality, fair competition, consumer and environmental protection, and innovation. We advocate for policies and marketplace practices that support these beliefs and values.

One Voice

Together, we FUELIowa!

The purpose of using a shared brand is to demonstrate the strength and scale of our network with one voice. By providing all FUELIowa members with a unified ‘stamp,’ we maximize our impact and visibility in the state of Iowa.


Please join us in promoting this shared brand by communicating it through your channels such as Facebook or other platforms like your website. Below are images you can use to support this effort. Don't see an image that represents your interests, give us a call at 515-224-7545. We will work to get you just what you need.


We also encourage you to like and follow us on Facebook and Twitter. The content we post can be easily shared on your respective company pages or tailored to to your specific circumstances. It is focused on building consumer support and appreciation for our industry while being fun and informative. 


Through one voice, we can increase the impact of our shared mission.

History

FUELIowa Began Amidst Controversy in 1935...

In 1935, both the refiners and many independent oil jobbers previously belonged to one statewide organization. Service station competition between the independents and the major refiners caused the break in 1937 that led the independents to form their own trade association called the “Iowa Independent Oil Jobbers Association”. In 1983, the association changed its name to “Petroleum Marketers of Iowa” and later added convenience stores to the name in 2001, becoming PMCI, Petroleum Marketers and Convenience Stores of Iowa. In 2019, PMCI re-branded to FUELIowa, The Voice and Resource for Iowa's Fuel Industry.

The 1930's fracture developed back when the major oil companies owned most of Iowa's bulk plants and service stations. Some independent jobbers claimed there was unfair competition because major oil was controlling prices on sites they owned. The independents aggressively looked for governmental help. The answer came in the form of a "chain store tax." Two thousand Iowa merchants, many of them independent oil jobbers, packed the 1935 Iowa House of Representatives to applaud speakers supporting one of the nation's highest chain store taxes. The law passed. Because of its lack of influence and finances, the newly formed group “Iowa Independent Oil Jobbers Association”, was not expected to succeed. Over time, the association of members not only succeeded, it now represents more than 2,000 independent business locations.

The association, FUELIowa, employs a professional staff that provides technical expertise to business owners and highly skilled negotiating on behalf of members to public policy makers. Because every business location in Iowa is owned and operated independent of major oil, consumers enjoy among the lowest fuel prices in the country. Consumers benefit from competition.


Over 80 Years of Serving
Members and Iowans with Fuel and Convenience

Board of Directors
Immediate Past Chair

Tessa (Fahey) Anderson

Rainbo Oil

Dubuque
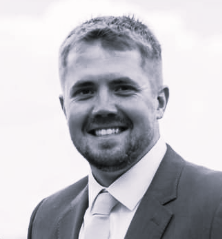
Chair

Nate Lincoln

Lincoln Farm & Home Service LLC

Glenwood
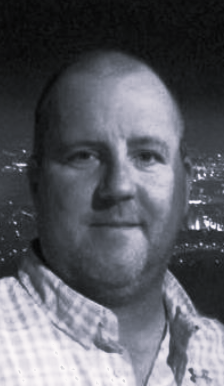
Vice Chair

Jason Stauffer

NEWCENTURY FS

Ames
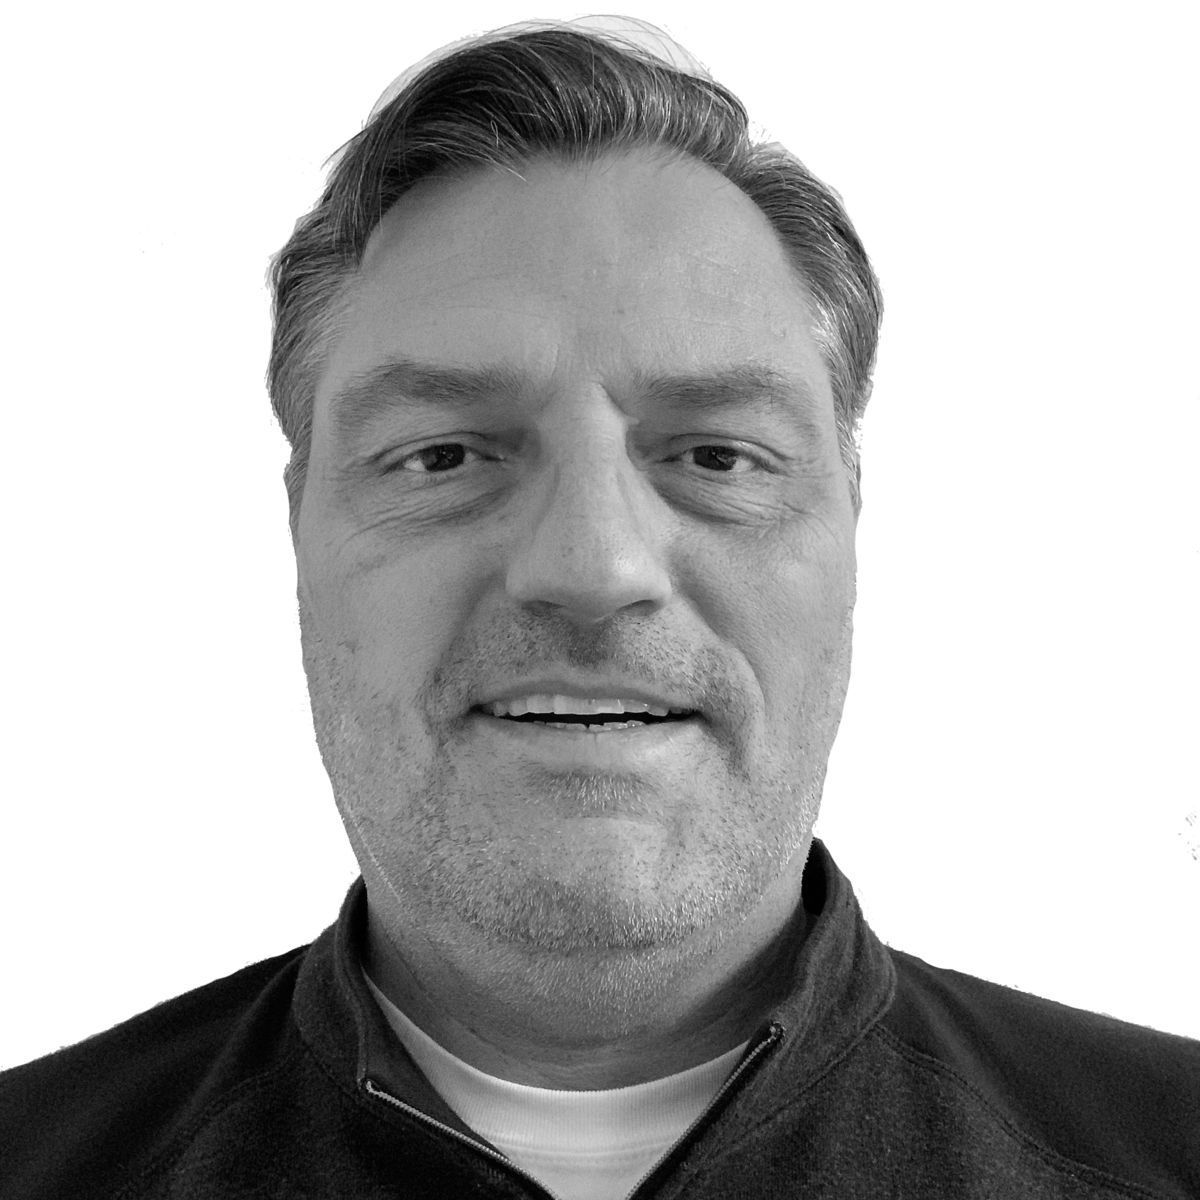
Treasurer

Dennis Jaeger

Molo Companies

Dubuque 
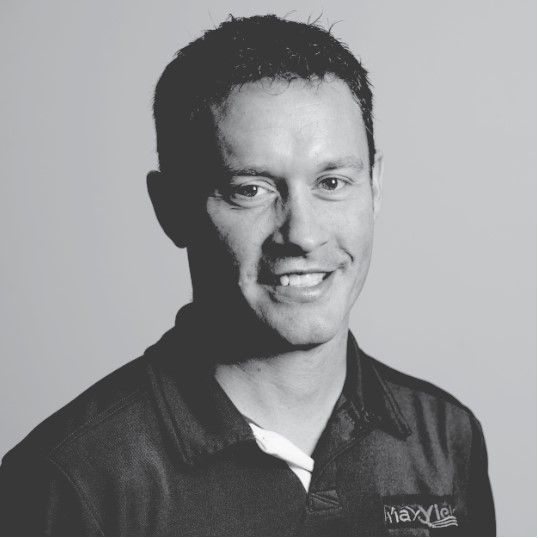
Director

Chad Besch

NEW Cooperative

Algona
Director

Don Burd

Otter Creek Country Store

Hiawatha
Director

Brett Kimmes

Kimmes Country Stores

Carroll
Director

Keith Olsen

Olsen Fuel Supply

Atlantic
Director

Dave Reif

Reif Oil Company

Burlington 
Director

Scott Richardson

Key Cooperative 

Roland
Director

Inder Singh

Brew Oil

Storm Lake
Director

Cody Staab

Casey's General Stores

Ankeny
Director

Nate Stumpf

HTP Energy

Onalaska, WI 
Associate Director

Kathy Gunlock

Core-Mark/Farner Bocken

Omaha, Nebraska
Associate Director

Cara Ingle

Unified Contracting Services, Inc

Des Moines
Associate Director

Kyle May

Reynolds American

Winston - Salem, NC
Associate Director

Ed Rogers

JF Petroleum Group

Des Moines

Staff
CEO


Gary Koerner

President, Government  Affairs

John Maynes

Director, 
Membership & Business Services

Jim Ewing

Director, Communications & Events

Sarah Bowman

Lobbyist

Marc Beltrame

Lobbyist

David Peck

Membership - Join Us!

It's easy and the value is incredible


Join 500+ FUELIowa member companies and take advantage of our industry leading advocacy efforts, service programs, and events. Get involved and help shape our industry!